Finding the best personal loan rates in 2026 for credit scores between 580 and 740 requires understanding how lenders price risk, where origination fees and prepayment penalties appear, and how to compare offers without harming your credit. This guide maps realistic APR ranges by score tier, explains how different lender types compete, clarifies fee structures, and outlines a step-by-step approach to secure a cost-effective personal loan.
Snapshot of 2026 personal loan APR ranges by credit score band
Actual annual percentage rate (APR) offers vary by lender, income stability, debt-to-income ratio, loan amount, and term. The following ranges reflect common outcomes in the U.S. market for unsecured personal loans in 2026, not guaranteed quotes. Always verify with each lender’s current disclosures.
- Credit scores 580–629 (poor to subprime): Expect higher pricing. Many approvals fall in the mid-20% APR to the legal or platform maximum (often up to about 36%). Lower rates within this band are less frequent and generally require strong compensating factors.
- Credit scores 630–689 (fair to near-prime): Typical outcomes cluster from the low-to-mid teens into the 20s. Applicants with stable income and low debt may see better-than-average offers, especially at credit unions.
- Credit scores 690–740 (good): Many qualifying borrowers see high single-digit to low-teen APRs, with the most competitive quotes often tied to shorter terms and autopay discounts. Rates can be higher for longer terms or higher loan amounts.
These bands are directional. A strong application can beat the midpoint of its tier, while elevated debt or longer terms can push pricing higher even with a good score.
Lenders compared: banks, credit unions, online lenders, and marketplaces
Personal loan pricing differs by institution type. Comparing categories helps narrow where to prequalify.
- Banks: Tend to favor customers with established relationships. Underwriting can be stricter, and funding may take longer than fintechs. Competitive for good credit borrowers, but fewer options for subprime.
- Credit unions: Often offer member-friendly rates and smaller fees, especially for fair-to-good credit. Membership eligibility rules apply. Some credit unions consider alternative factors and may be more flexible on near-prime files.
- Online lenders (fintechs): Fast applications, soft-pull prequalification, and quick funding are common. Broadest credit box across 580–740, with transparent ranges and clear fee disclosures. Pricing varies widely by platform.
- Marketplaces and loan aggregators: Provide multiple prequalified offers with a single form and soft credit check. Useful for rate discovery, but read each lender’s final terms before accepting.
- Peer-to-peer and hybrid platforms: May price competitively for good credit and smaller loan sizes. Availability can be state-dependent, and funding speed varies with investor demand.
For many borrowers in the 580–740 range, credit unions and reputable online lenders are often the sweet spot for balancing rate, speed, and acceptance criteria. However, relationship discounts at a primary bank can be valuable for good credit applicants.
APR ranges, origination fees, and prepayment penalties explained
Comparing personal loans requires more than looking at the advertised rate. Focus on APR, fees, and contract terms that affect total cost.
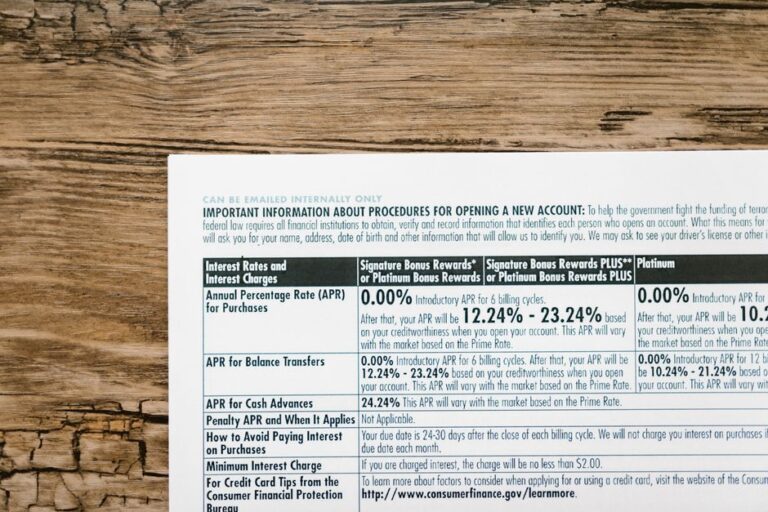
- APR (Annual Percentage Rate): Reflects the interest rate plus mandatory finance charges spread over the loan term. It is the most comparable pricing metric between offers of the same amount and term.
- Origination fee: A one-time charge, often a percentage of the loan amount, deducted from disbursement or added to the balance. In 2026, unsecured personal loan origination fees commonly range from 0% to the low double digits depending on credit profile, platform policies, and term. Zero-fee options exist, but some lenders offset fees with higher APRs.
- Prepayment penalty: A fee for paying off early. Many mainstream U.S. personal loan providers do not charge prepayment penalties on unsecured loans, but terms vary. Always confirm whether the contract includes any precomputed interest or early payoff fees.
- Other fees: Possible charges include late fees, insufficient funds fees, and paper statement fees. Autopay discounts are common and can reduce the rate, typically by a small margin when available.
When comparing quotes, compute the repayment schedule with and without fees to see the true cost. If a lender nets the origination fee from the disbursement, ensure the received cash still meets your need.
How term length, loan size, and collateral affect your personal loan APR
Beyond credit score, structural choices directly influence pricing and approval odds. Consider the following dynamics before you apply.
- Term length: Shorter terms frequently carry lower APRs but higher monthly payments. Longer terms can ease cash flow while raising total interest paid.
- Loan amount: Larger loans can trigger different underwriting tiers. Some lenders improve pricing for mid-range amounts, while others add risk premiums as balances grow.
- Secured vs. unsecured: Secured personal loans (for example, with a savings or vehicle lien) may reduce APRs relative to unsecured offers but introduce collateral risk if you default.
- Debt-to-income ratio (DTI): Lower DTI strengthens pricing leverage across all score bands. Reducing existing balances before applying can help.
Optimizing these variables can move an offer from the high end of a range toward the low end, especially for near-prime profiles.
How to shop for the best personal loan rates in 2026 without hurting your credit
Efficient shopping preserves credit health and maximizes your negotiating position. Follow a disciplined process and document every quote.
- Use soft-pull prequalification: Start with lenders and marketplaces that show estimated APRs without a hard inquiry. Verify that the previewed range reflects your exact desired amount and term.
- Limit hard pulls: Submit full applications only to top candidates after reviewing disclosures. Spacing hard inquiries and keeping them to the minimum can help protect your score.
- Standardize comparisons: Compare equal loan amounts and terms across offers. Convert all pricing to APR and calculate total repayment.
- Confirm fee treatment: Ask whether origination fees are financed or net-funded and whether any early payoff costs exist.
- Leverage relationship and autopay discounts: Enroll in autopay when it reduces APR and consider institutions where you keep deposits for possible loyalty benefits.
Rate shopping is most effective when you gather multiple prequalified quotes on the same day and then secure final terms within a tight window.
Strategies to lower your rate before you apply
Preparation can shift you into a better pricing tier, sometimes more than the difference between competing lenders. Consider targeted steps that can reasonably be completed before submitting applications.
- Reduce revolving utilization: Paying down credit card balances to lower utilization can influence many credit scores.
- Stabilize income and DTI: Document income consistency and eliminate small installment debts if possible.
- Clean up inaccuracies: Dispute errors on your credit reports with the bureaus and confirm corrections are posted before applying.
- Choose a shorter term you can afford: A shorter term often unlocks better APRs and reduces total interest cost.
For a complete roadmap to boosting your profile, see how to improve your credit score before applying for a personal loan and align your application timing with expected score updates.
Comparing offers: a simple, transparent checklist
A structured review prevents costly oversights. Use this quick checklist to evaluate each quote consistently.
- APR and base rate: Note both if shown. The APR is the basis for comparison.
- Total of payments: Multiply monthly payment by the number of months and add any one-time fees not included in APR.
- Fee inventory: Origination, late, NSF, paper statements, expedited payments, and check processing.
- Prepayment terms: Confirm whether interest accrues daily and whether any early payoff charges exist.
- Funding timeline: Expected disbursement date and whether net funding applies after fees.
- Hard inquiry timing: When does the lender run a hard pull and can it be delayed until acceptance?
For a broader due-diligence view, consult the essential checklist for securing your first personal loan and align it with your borrowing goals.
Illustrative total-cost scenarios (for comparison only)
The following examples are hypothetical and for educational comparison. They show why APR and fees must be considered together. They are not quotes.
- Scenario A: $10,000 loan, 36 months, 12.99% APR, 0% origination. Approximate monthly payment is in the mid-$330s, with total repayment in the low $12,000s.
- Scenario B: $10,000 loan, 36 months, 10.99% interest rate, 6% origination fee net-funded. You receive $9,400. Monthly payment is similar to Scenario A on the full $10,000 balance, but your effective cost is higher if you needed the full $10,000 in hand.
- Scenario C: $10,000 loan, 60 months, 15.99% APR, 0% origination. Monthly payment drops significantly relative to 36 months, but total interest rises meaningfully over five years.
Key takeaway: analyze cash received, monthly payment, and total of payments together. A lower stated rate can cost more once fees and term are factored in.
Common 2026 pitfalls: fees, add-ons, and contract traps
Market competition is strong, but some offers hide avoidable costs. Watch for the following before you sign.
- High origination with net disbursement: If you need a specific cash amount, a high fee can force borrowing more than planned.
- Credit insurance add-ons: Optional products can increase the APR-equivalent cost. Only opt in after assessing necessity and value.
- Precomputed interest or Rule of 78s: Early payoff savings may be limited under certain interest calculation methods. Confirm interest accrual is simple interest, calculated daily.
- Introductory discounts with conditions: Autopay or relationship rate reductions can be reversed if you cancel the linked service.
- Late fee structures: Understand the grace period and whether fees are flat or percentage-based.
Careful document review helps avoid surprises. If any term is unclear, ask for written clarification before accepting an offer.
When a personal loan is not the best fit
Depending on your score and debt load, alternatives may reduce costs or risk. Evaluate these options before committing.
- 0% APR or low-interest balance transfers: Useful for consolidating revolving debt if you can repay within the promo period and manage fees.
- Credit union lines of credit: Flexible access and potentially lower costs for good-credit members.
- Debt management plans: For high revolving balances, nonprofit counseling can negotiate concessions without new borrowing.
- Secured loans: Collateralized options may lower APRs, but weigh asset risk carefully.
If you decide a personal loan still fits, refine your criteria with how to choose the right personal loan for your financial goals and avoid common traps highlighted in top 5 personal finance mistakes to avoid when taking out a loan.
How to choose among final offers
Once you have two to four strong quotes, apply a weighted decision approach to break ties and align with your goals.
- Primary weight: total cost and APR: Favor the lowest verified APR for the same amount and term, all fees included.
- Secondary weight: flexibility and speed: Consider payment date change policies, hardship options, and funding timeline.
- Tertiary weight: service quality: Review customer support availability and digital account management features that matter to you.
- Risk controls: Choose simple-interest loans without prepayment penalties and with transparent fee schedules.
Document your rationale and keep copies of disclosures and the final agreement for your records.
FAQ: Best personal loan rates for credit scores 580–740 in 2026
What is a good personal loan APR for a 700 credit score in 2026?
With a 700 score and stable income, many borrowers see high single-digit to low-teen APRs, depending on term length and lender type. Actual offers vary, so obtain multiple prequalified quotes to find the most competitive rate you can qualify for.
Do most personal loan lenders charge prepayment penalties?
Many mainstream U.S. unsecured personal loan providers do not charge prepayment penalties, but policies are not uniform. Confirm your contract specifies no early payoff fees and that interest accrues daily on a simple-interest basis.
How big are origination fees in 2026?
Origination fees vary by lender and profile. It is common to see fees range from 0% to the low double digits. Some lenders advertise no origination fee but may price interest higher. Compare total cost, not fees in isolation.
Will a soft-pull prequalification affect my credit score?
A soft credit check does not impact your credit score. A hard inquiry typically occurs when you submit a full application or accept an offer. Ask lenders when they perform the hard pull.
Is a longer term better if the monthly payment is lower?
Longer terms reduce monthly payments but usually increase total interest paid. If cash flow allows, a shorter term can lower APRs and reduce overall cost. Choose the shortest term that fits your budget without risking late payments.
For deeper guidance on structuring your application and matching a loan to your objectives, explore how to choose the best personal loan for your unique financial needs and integrate those steps into your rate shopping process.