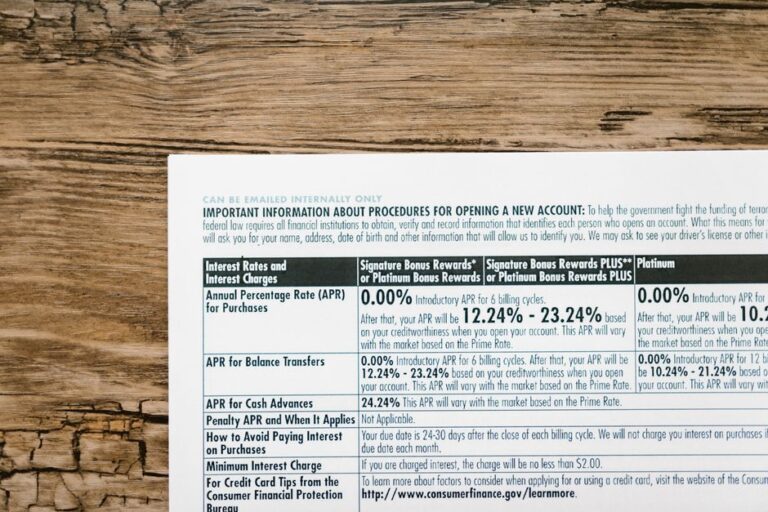
Best personal loan rates for credit scores 580–740 in 2026: lenders compared, APR ranges, origination fees, and prepayment penalties

Debt consolidation is a financial strategy that combines multiple debts into a single loan, usually to secure a lower interest rate or a more manageable payment plan. This approach can be beneficial for individuals struggling with high-interest debts, such as credit cards or personal loans. By consolidating your debts, you can simplify your finances and potentially save money over time.
Debt consolidation involves taking out a new loan to pay off existing debts. This can be done through various means, including personal loans, balance transfer credit cards, or home equity loans. The primary goal is to reduce the overall interest rate and streamline payments into a single monthly obligation.
Consolidating your debt requires careful planning and execution. Below are the essential steps to guide you through the process of achieving financial freedom.
Start by gathering all your financial statements. List out your debts, including the total amount owed, interest rates, and monthly payments. This assessment provides a clear picture of your current financial situation and helps you determine if consolidation is the right option for you.
There are several methods for consolidating debt, each with its advantages and disadvantages:
Before proceeding, calculate the total costs associated with each consolidation method. Consider any fees, interest rates, and the length of the repayment period. Weigh these costs against the potential savings to determine the best course of action.
Once you’ve selected the best option, apply for the loan. Lenders will typically require documentation of your income, credit history, and existing debts. Ensure that you understand the terms and conditions before signing any agreements.
After securing the consolidation loan, use the funds to pay off your existing debts immediately. This step is crucial to avoid accumulating additional debt while managing your new loan.
Establish a budget that accommodates your new monthly payment. Include all necessary expenses and ensure that you allocate funds to your debt repayment. Stick to your budget to avoid falling back into debt.
Regularly review your financial situation. Track your payments and adjust your budget as needed. Celebrate small milestones to maintain motivation throughout your debt repayment journey.
While debt consolidation can be an effective strategy, there are common pitfalls to avoid:
No, debt consolidation may not be suitable for everyone. It is essential to assess your financial situation and consider factors such as credit score, debt amounts, and personal financial habits.
Initially, applying for a new loan may cause a slight dip in your credit score. However, consistent payments on the consolidation loan can improve your score over time.
The time required to pay off consolidated debt varies based on the loan terms and your repayment plan. It can range from a few months to several years.
Yes, but be cautious. Consolidating student loans with other debts may change the repayment terms and interest rates. Review your options carefully.
If you are struggling to make payments, contact your lender immediately to discuss options. They may offer deferment, forbearance, or alternative repayment plans.
While debt consolidation can offer relief, it is essential to understand the potential risks involved. Many individuals may feel tempted to accumulate new debt after consolidating their existing obligations, which can lead to a cycle of financial instability.
One of the primary risks is the temptation to use credit cards or loans again, resulting in a higher overall debt load. It is crucial to avoid this trap by creating a budget that prioritizes debt repayment.
Some debt consolidation loans come with high fees or prepayment penalties. Always read the fine print and consider these costs when evaluating your options. Hidden fees can negate the benefits of consolidation.
While debt consolidation can improve your credit score over time, it may initially cause a slight decrease due to the hard inquiries and changes in your credit utilization ratio. Monitoring your credit report regularly is advisable.
To maximize the benefits of debt consolidation, consider the following strategies:
By adhering to these guidelines, you can navigate the debt consolidation process more effectively and achieve financial stability.