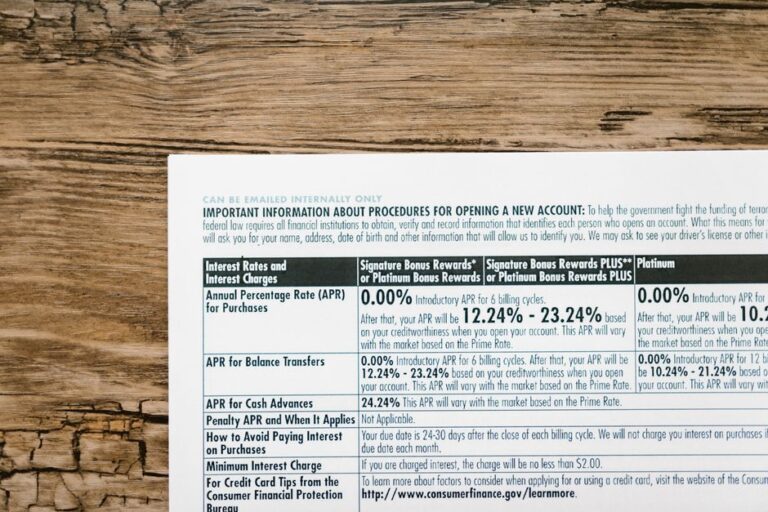
Best personal loan rates for credit scores 580–740 in 2026: lenders compared, APR ranges, origination fees, and prepayment penalties

Understanding debt consolidation options is essential for anyone looking to optimize their personal finances. By managing debt effectively, individuals can alleviate financial burdens, ultimately paving the way toward financial stability. In this comprehensive guide, we will explore various debt consolidation methods, empowering you to make informed choices regarding your financial future. This article will delve deeper into each method, helping you identify which approach aligns best with your circumstances.
Debt consolidation is the process of combining multiple outstanding debts into a single loan or repayment plan. This strategy simplifies the management of payments and may result in lower interest rates, which can ease financial strain. By consolidating debts, individuals not only improve their credit scores over time but also experience a reduction in stress that often accompanies managing several monthly payments. Consider it akin to streamlining a cluttered workspace into a single organized file; it makes recalling information easier and enhances overall productivity.
When exploring debt consolidation, it is crucial to understand the different methods available. Each comes with unique advantages and considerations for your financial landscape. Below are the most common options:
Choosing the right debt consolidation method requires careful evaluation of your financial situation. Each option comes with its benefits and drawbacks, all of which can profoundly impact your long-term financial health. Keep the following key factors in mind during your evaluation:
It is imperative to compare interest rates across various consolidation options. A lower rate can drastically reduce your overall payments, allowing you to pay off your debt faster. For example, if you have multiple credit card debts averaging 20% interest and move to a debt consolidation loan at 10%, your monthly payments will drop significantly.
Be vigilant regarding any potential fees associated with debt consolidation methods. Some lenders or services may charge fixed fees or percentages that could negate the benefits gained from consolidating. Make sure to factor in these costs in your overall assessment, considering them as part of the debt management landscape.
Know how each option will affect your credit score. Some methods, like debt settlement, can initially lower your score, but sticking to a strict repayment plan afterward can lead to improvements. Conversely, responsibly using a balance transfer card could enhance your score over time as you reduce your debt and maintain low balances.
Successfully consolidating debt requires a structured approach. Follow these steps to effectively regain control of your financial situations:
The optimal method varies based on your specific financial circumstances. A debt consolidation loan may be ideal for individuals with good credit, while those with lower scores might find a Debt Management Plan more beneficial. Tailoring your approach can significantly influence the outcome.
Initially, you might see a slight drop in your credit score. However, if you remain diligent with timely payments, you may eventually experience substantial improvements over time as your overall debt decreases.
The time it takes to complete debt consolidation can fluctuate based on the chosen method and personal financial habits. Generally, it may take several months to a few years to achieve a debt-free status following consolidation.
Yes, potential risks include high fees, the risk of accruing additional debt without a change in spending habits, and a temporary reduction in your credit score during the initial phase of consolidation.
In general, student loans and credit card debts are treated differently. However, some lenders may offer debt consolidation loans that allow you to combine both types, depending on their terms and conditions.
In conclusion, understanding and evaluating the options for debt consolidation is crucial for improving your financial health. Whether you choose a loan, credit card transfer, or another method, informed decision-making is essential for successful debt management. Take the first step towards financial recovery by exploring your options and implementing a plan that aligns with your needs.
If you’re ready to take control of your finances and explore the world of debt consolidation, visit our website today. Empower yourself with the knowledge and tools necessary to make your financial future bright.